Essay Features
How the GP/LP Structure Works in Real Estate Deals
Understanding how GPs and LPs split control, risk, and profits in property deals.
In property transactions, the GP/LP framework pairs hands-on management skill alongside investor funds while dictating the allocation of authority, risk exposure, and earnings. This works when those rules reinforce each other. Assessing such an arrangement thus demands looking beyond anticipated financial outcomes. One must grasp the interplay among governance duties, sponsor pay, and profit tiers across the deal's entire lifespan.
Why the GP/LP structure exists as a solution to a specific problem
A real estate sponsor may possess the expertise for a major property deal yet lack the funds to purchase it. This skill set encompasses deep market insight, established lender connections, and the ability to oversee real estate on a full-time basis. The capital provider confronts the reverse limitation. Institutional investors like pension funds, plus wealthy families and individuals, often possess capital for deployment while lacking interest in managing the property themselves.
Those limits are made complementary by pairing a GP with an LP. The GP handles finding, vetting, funding, and running the deal, while LPs put up most of the equity. LPs allow the GP an outsized slice of the upside in exchange for its execution and to align pay with results. Through this setup, passive investors can access large institutional property deals they could not pursue on their own.
How the legal wrapper translates the partnership into enforceable roles
That deal structure has to sit inside an entity that allocates decision rights and caps liability. Sponsors commonly choose a limited partnership or manager-managed LLC because either form separates the operator’s role from that of capital-only backers. The GP, or its managing LLC, usually funds one to five percent of the deal and keeps authority over investment choices. LPs provide most of the equity but do not take management authority. Putting in more money still leaves them outside everyday control of operations.
Liability works on a separate split. LPs risk only what they contribute, so partnership debts beyond that sum are not their responsibility. Today's arrangements typically place an LLC around the GP to protect private wealth, though that same GP still backs property-level debt personally. Such a pledge introduces risk absent from what limited partners face. Capital moves through SPVs, or special purpose vehicles, setting up one for each property or portfolio and confining exposure to individual assets while money funds purchases and operating needs.
These roles become binding through the partnership agreement, or the operating agreement in the case of an LLC. It spells out the GP's independent decision-making authority, matters needing LP approval, the mechanics of capital calls and distributions, and the process for settling disputes. Taking money from passive investors triggers securities laws, so syndications run under the Securities Act of 1933's Section 4(a)(2) exemption, and Regulation D gives sponsors the safe harbor they typically rely on to sidestep full SEC registration. One of its rules, 506(b), permits unlimited accredited investors and caps non-accredited investors at 35, all without general solicitation. The other, 506(c) allows public advertising but limits participation to accredited investors, demanding reasonable verification steps, where third-party confirmation serves as one optional approach.
What the GP actually does and how that workload justifies disproportionate economics
The GP shoulders a workload that starts before any property brings in income. It identifies and vets opportunities, assembles the financial analysis framework, and runs due diligence through site visits, third-party assessments, counsel reviews, and rent-roll examinations. It then works out the purchase terms and locks in financing. Because the GP signs as personal guarantor of the debt, the responsibility goes beyond securing financing: the sponsor is pledging operating capacity along with a financial risk that LPs never bear.
Once the deal closes, attention shifts from judging the business plan to carrying it out. During the hold, the GP manages the asset, improvements, vendors, leases, and reporting to investors. At exit, the GP chooses when to sell, handles negotiations, closes the sale, and pays out proceeds as the agreement requires. Because the GP performs this work, its pay does not merely track its equity share. LP funding matters, but money on its own cannot carry an acquisition through to a realized return.
Sponsors receive payment throughout each stage via this layered fee structure. Acquisition costs usually consume between one and three percent of the purchase price, whereas asset management claims between one and two percent of capital deployed or revenue. Such charges fund deal origination, execution, and continuous supervision, yet sponsors collect them regardless of investment results. When structured properly, these charges sustain day-to-day management instead of acting as the primary wealth-building opportunity for sponsors. Instead, sponsors build real wealth through carried interest (the promote), claiming between twenty and forty percent of gains once the preferred return hurdle clears, which ties their payout to the sequence of investor distributions.
How the waterfall sequences every dollar from exit back to its rightful owner
The waterfall works as a series of distribution gates. Under this arrangement, LP investors recover their initial capital at the first gate before the GP shares in waterfall distributions. Next, investors receive their negotiated yearly preference calculated against still-outstanding LP invested capital. Promoted interest becomes payable only once the required senior distributions have been satisfied. This difference is important: residual-profit participation does not entitle the holder to a slice of all exit proceeds.
The second gate's strength hinges on how the preferred return accrues. With a cumulative preferred return, any cash shortfall rolls over to future periods, blocking the GP from collecting promoted interest until that deficit is cleared. If the preferred return is non-cumulative, however, any shortfall vanishes permanently. When cash generation lags or an asset faces distress, that gap can erase the yield the headline preferred rate seems to promise.
Picture a sale coming after a stretch in which the cash generated failed to fully cover the preferred return as it accumulated. The waterfall returns LP capital first, then pays the preferred return from available proceeds, accrued shortfalls included. If the money runs out there, nothing residual is left for the promote. Once those amounts are covered, any surplus flows into the agreed profit-sharing arrangement, with the catch-up provisions governing how it is divided. Identical proceeds from one asset can thus yield the GP very different compensation, hinging on which hurdles have been cleared.
Equity splits may adjust as performance clears one IRR hurdle after another. At the lower tiers, LPs usually receive more of the economics, but the GP’s share increases in the higher bands. Carry therefore magnifies the payoff from beating the target, offering little above the hurdle but a larger share once returns are well beyond it. So read the preferred return alongside catch-up mechanics and the tiered split schedule.
Those limits are made complementary by pairing a GP with an LP.
How GP co-investment creates a third position between the standard GP and LP roles
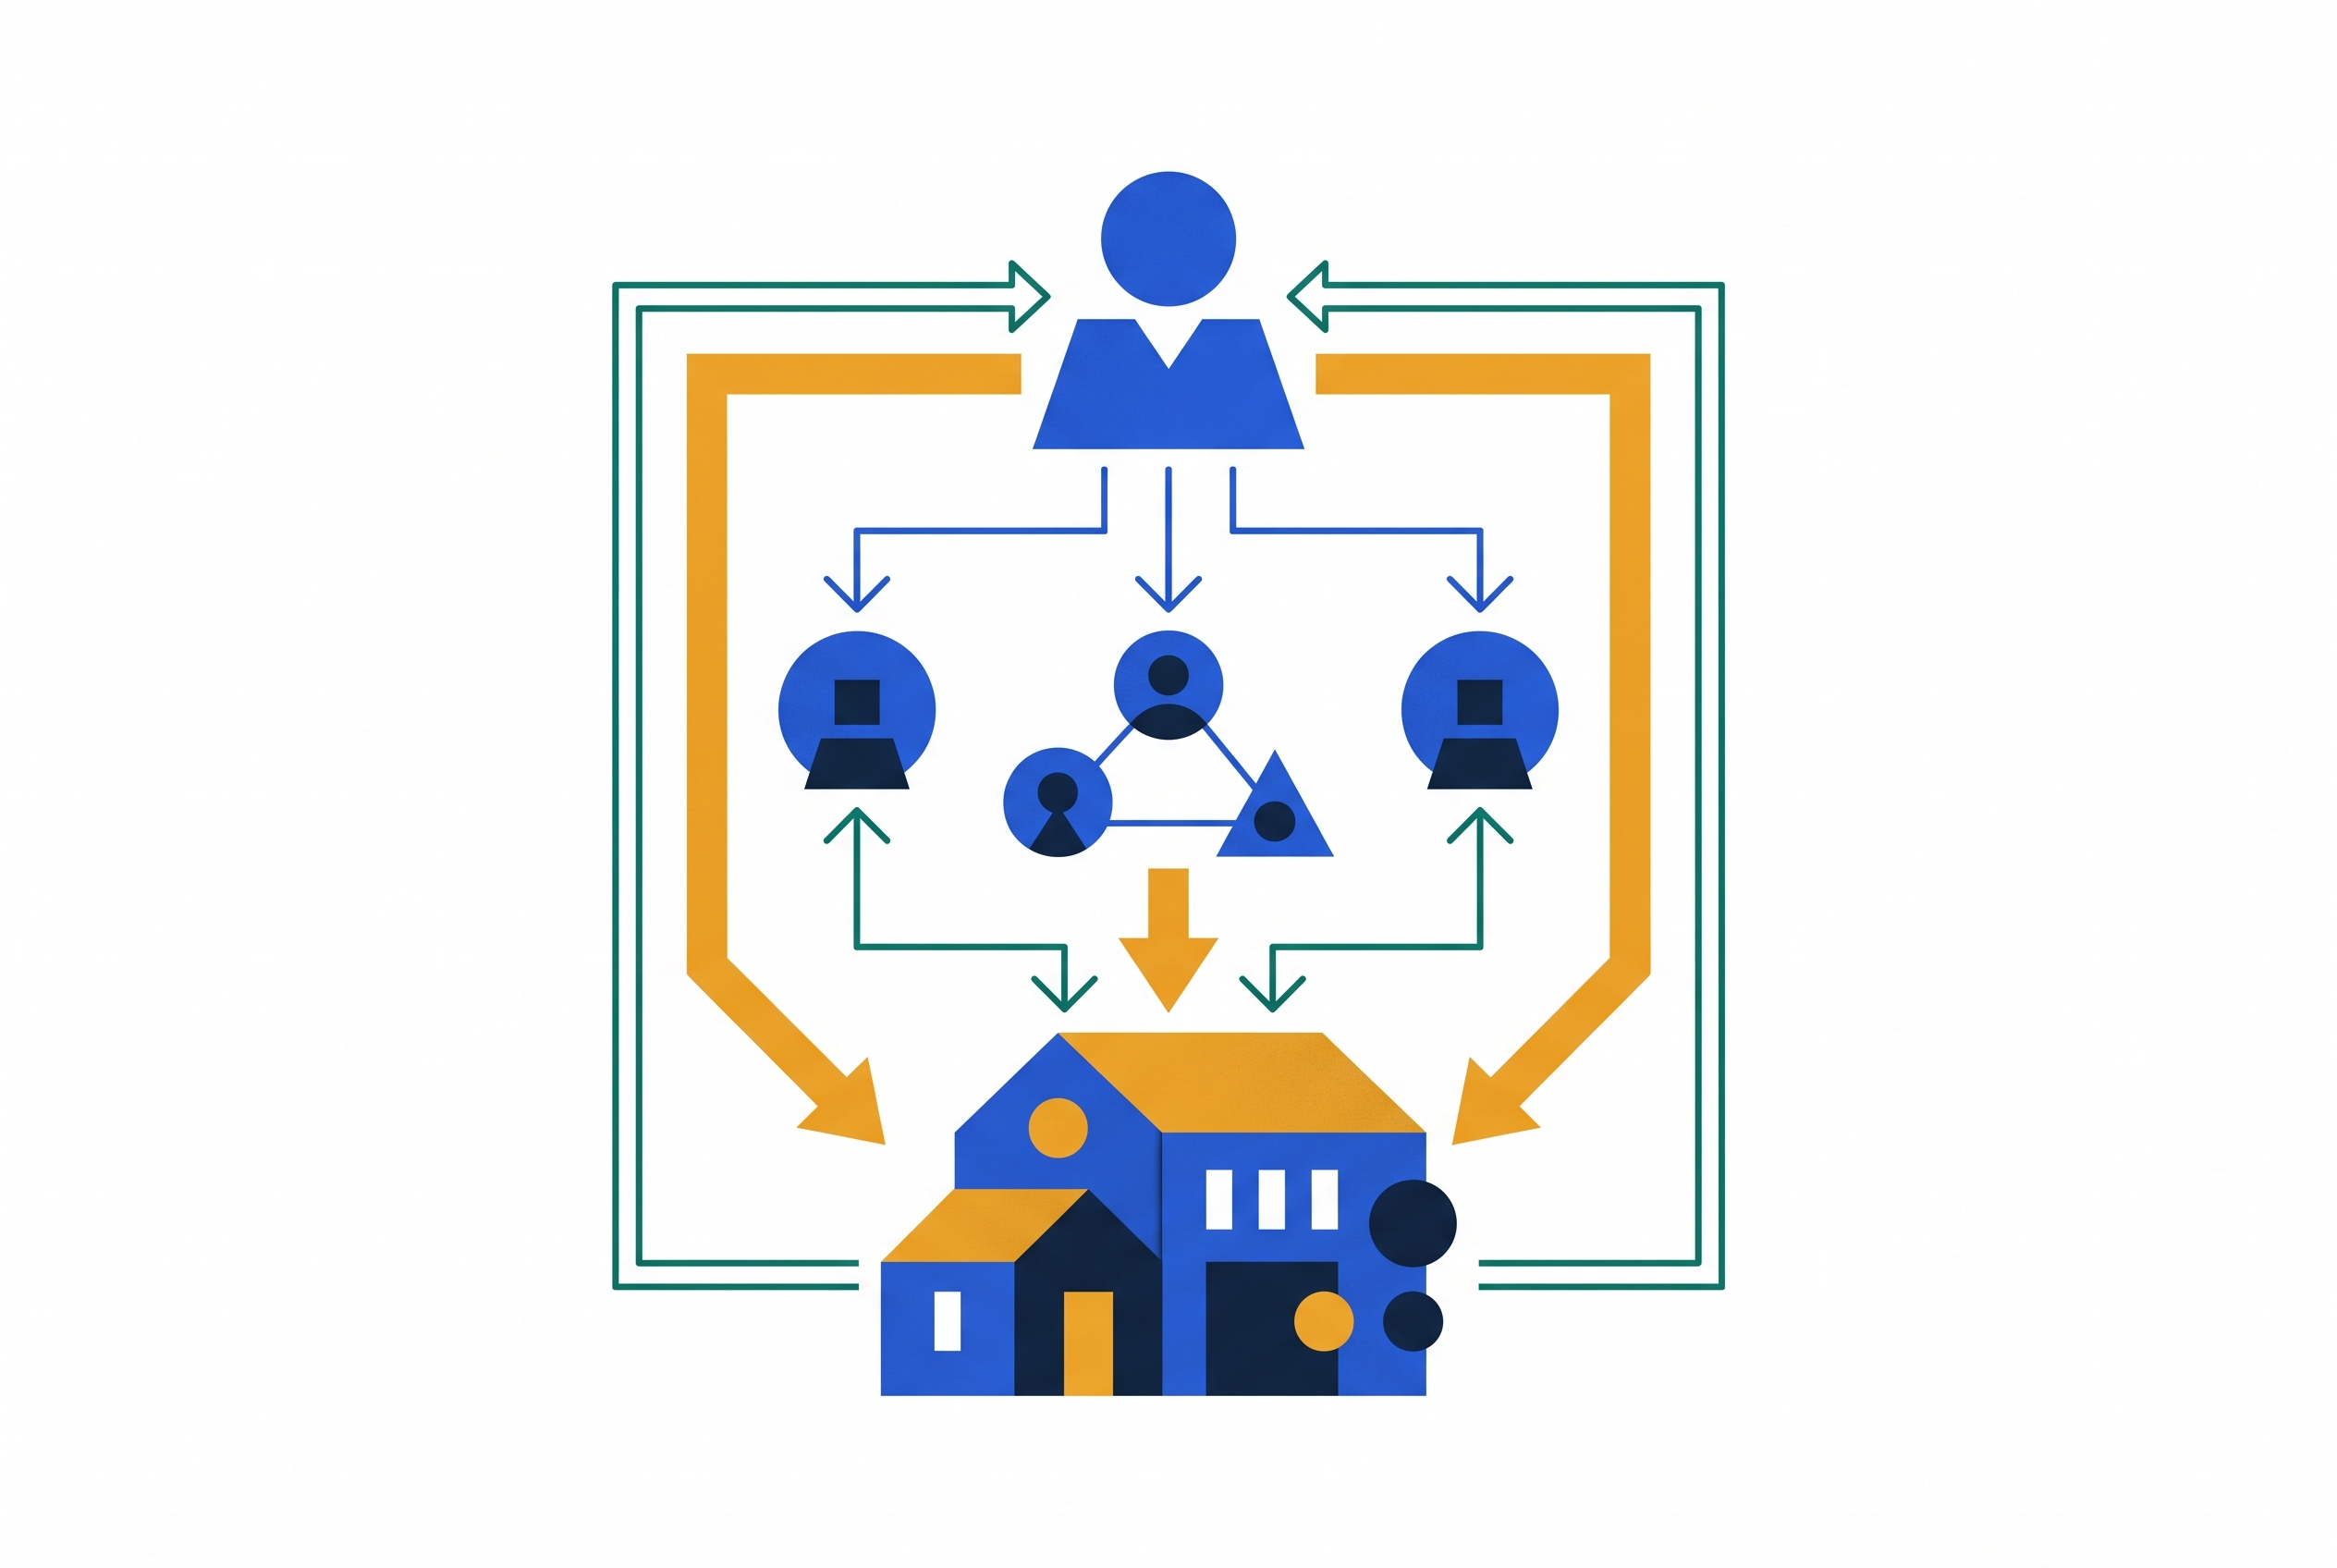
The usual divide separating sponsor from passive investor misses some of the routes by which capital reaches a deal. A sponsor faces limits from both the equity it must commit itself and the LP capital it still has to raise. Instead of concentrating its own capital in one deal, the sponsor can invite outside investors onto the GP side. These backers, typically wealthy individuals, fund a slice of the GP's required equity stake and receive a portion of its promote in return. Though these backers provide funding, their stake in the deal sits apart from a typical LP's.
This arrangement provides the GP sufficient funding to close while preserving resources for a separate deal. Sharing carry is rational since the sponsor keeps a stake in a deal made possible by that co-investment. Co-investing partners who join the promote may earn more on each dollar invested compared with ordinary limited partner stakes whenever performance is strong. Such gains still rank below the limited partner distribution sequence. It also entails greater risk when the GP entity bears initial shortfalls, as those investing alongside the sponsor face write-downs ahead of LP capital.
Co-investment thus introduces a separate role, rather than dissolving the divide separating managers from passive owners. The economics instead reflect project-level returns together with what accrues to the GP. This structure may increase how much the sponsor can commit, yet alignment analysis turns on where that commitment comes from. A GP stake should therefore be weighed differently from funds the sponsor contributes directly.
Where the structure's incentive alignment breaks down and how the market has responded
Stacking fees can render deal completion appealing even if lasting LP value is in doubt. When upfront and ongoing fees make up too large a share of the sponsor's economics, chasing deal volume can rival investment performance as the goal. The promote pays off when things go well, yet fees already earned stay earned.
Clawbacks deal with a separate timing problem: carry may be paid out before the fund’s final results are clear. If the fund ultimately misses the hurdle, LPs can claw back carry already paid. But a contractual right to get money back is not the same as collecting it in practice. When the true-up arrives, those payments may no longer be sitting with the GP. Getting it back from individual principals may prove difficult, so enforcement matters as much as the obligation itself.
In GP-led continuation vehicles, pricing is where the conflict becomes most acute. If the sponsor rolls a holding out of an aging fund and into another sponsor-controlled vehicle, its fiduciary obligations run to the selling LPs, who benefit from the highest possible sale price. But a lower acquisition price gives the new vehicle more upside. In June 2024, the Fifth Circuit invalidated Private Fund Adviser Rules issued by the SEC, eliminating mandatory fairness or valuation opinions just as continuation vehicles hit a record scale. That stripped away a procedural safeguard, but not the underlying conflict.
New agreements now routinely include key-person terms, tougher clawbacks, and fuller disclosure obligations in response. These provisions target vulnerabilities that the waterfall does not close. Even so, having them in place does not show that LPs have enough protection, especially at large institutional funds with uneven bargaining power. Its practical value still depends on the rights investors actually receive and the remedies they can use.
What both GPs and LPs should examine before entering any deal under this structure
LPs should begin diligence by following how property-level cash moves through to their distributions. Start by checking whether the pref is cumulative, and then test the catch-up mechanics and IRR breakpoints used for promote allocations against credible return scenarios for that asset type. Assess the sponsor promote together with every layer of fees, from acquisition and asset management to construction and disposition. These fees come out ahead of LPs receiving waterfall distributions. LPs should also read the private placement memorandum for any language giving the GP post-commitment authority to revise fees.
Governance requires separate scrutiny since distribution rights do not determine who controls a disputed decision. Check what the contract lets the GP do unilaterally versus what requires LP sign-off or LPAC authorization, especially for asset sales and continuation deals. Determine if clawbacks operate fund-wide or per principal and which enforcement route governs once carry is paid out or put back in. With continuation vehicles, scrutinize conflicting positions held by management, confirm whether independent valuation or fairness opinions were secured, and review how the LPAC sanctioned the deal. Such inquiries reveal if contractual safeguards hold up when priorities conflict.
GPs should focus on proving their commitment is credible and the deal terms are transparent. The size of the co-investment, measured against the transaction and the firm’s wider portfolio, signals alignment. A prudent approach to the hurdle rate, clawback mechanics, and profit-sharing bands can bolster LP trust in the initial fundraising phase. Delivering consistent reports, establishing a transparent valuation process, and quickly revealing material changes smooths LPAC interactions while supporting subsequent capital raising.
Such terms need clear articulation ahead of any fund deployment, since every clause addresses a distinct facet of one shared arrangement. Granting control while lacking genuine oversight results in an unfinished financial agreement. Coupling that control with binding safeguards for backers renders the split of responsibilities viable. GP compensation should ultimately come from LP performance.
Notes
- GP LP Structure
Provided foundational explanation of the GP/LP structure, including roles, equity splits, fee types, and waterfall distribution mechanics.